Will homeowners insurance cover a 15 year old roof, or is age enough to sink a claim? A 15-year-old roof isn’t automatically excluded from coverage. The outcome often depends on how the damage happened, the roof’s condition, and your policy terms. A sudden storm may be treated differently from gradual wear, but the insurer will review the circumstances before deciding whether the damage is covered.
Policy terms such as actual cash value and replacement cost can affect how a claim is settled. Deductibles and exclusions matter, too. This guide explains which details to review and what records and photos can help you prepare. It also covers what to expect from a professional roof assessment. For homeowners in Huntsville, Madison, Owens Cross Roads, Gurley, and Athens, an inspection can document visible conditions and possible storm damage, helping you understand practical next steps without promising a coverage decision.
Key Takeaways
- Roof age alone doesn’t determine whether damage is covered. The policy, roof condition, and cause of damage all matter.
- Actual cash value and replacement cost can affect a roof claim. Review the policy’s valuation terms and any roof-specific provisions.
- Compare signs of storm damage with signs of gradual wear, then gather relevant photos, repair records, and policy information.
- Before reporting damage, document what you can see and take safe steps to prevent further harm to your home.
- A professional roof assessment can document visible conditions and help you understand practical next steps, but it can’t guarantee a claim outcome.
Will homeowners insurance cover a 15-year-old roof? Start with the short answer
A 15-year-old roof isn’t automatically covered or excluded because of its age. If you’re asking, will homeowners insurance cover a 15 year old roof, the answer depends on your policy, the roof’s condition, what caused the damage, and the details of the claim. Insurers may assess storm damage differently from deterioration that developed over time. The policy and evidence determine how the insurer evaluates the loss.
There’s a difference between having an active policy and having coverage for a particular roof problem. A policy can remain in force while excluding certain damage or limiting how a roof claim is settled. A roofer can inspect the roof and document visible conditions, but only the insurer can determine whether a specific claim is covered. An inspection can clarify what’s present, not promise approval.
Does a 15-year-old roof automatically lose insurance coverage?
No single age answers every coverage question. The insurer may consider the roof’s condition, the reported cause of damage, and the relevant policy language together. For example, evidence of a sudden event and signs of long-term deterioration may prompt different questions during a claim review. Age may be part of the assessment, but it doesn’t by itself establish what caused the damage or determine whether it’s covered.
Start with your declarations page, which summarizes key policy details, then read the policy wording it refers to. Since homeowners insurance policies define coverage through specific terms and conditions, your own documents matter more than a general rule about roof age.
What should a homeowner check in the policy?
Look for the sections on covered causes of loss, exclusions, deductibles, and how roof damage is valued. Check for endorsements or roof-specific limitations as well. Their effect varies by policy, so don’t assume another homeowner’s coverage or a general online explanation matches yours. Review the current wording that applies to your home and the reported damage.
- Actual cash value (ACV): The settlement may account for depreciation, so it may be less than the cost to replace the roof.
- Replacement cost (RCV): The policy may use replacement-cost terms, subject to its conditions and limits.
- Deductible and exclusions: These can affect what the insurer pays, even when a loss is otherwise covered.
These are possible settlement approaches, not guarantees. If the wording is unclear, ask your insurer to explain how it applies to your roof and the reported damage. Keep the policy documents handy because they’re the starting point for understanding your next steps.
How roof age, condition, and policy terms shape an older-roof claim
A claim review looks at more than the roof’s installation date. The insurer may consider the reported event, visible damage, the roof’s condition before the event, repair or maintenance history, and the applicable policy language. These details can help distinguish damage associated with a sudden event from deterioration that developed over time. A roofer can document observable conditions, but the insurer decides how the evidence fits the policy.
Roof age is one factor. The policy and documented cause of damage guide the coverage review. There’s no universal age cutoff that determines every claim. Two roofs of the same age may differ in condition, repair history, and policy terms. For background on how insurers may approach insuring an older roof, Policygenius discusses roof age and possible coverage considerations. Your own policy controls your claim.
Why actual cash value and replacement cost matter
The settlement method can affect how a covered loss is valued. With actual cash value, depreciation may be factored into the amount for the damaged roof, depending on the policy. Replacement cost is a different settlement basis, but it doesn’t automatically mean full payment for a replacement. Policy conditions, limits, exclusions, and the deductible still matter.
Check the policy’s roof-specific provisions and settlement terms rather than relying on a general description of ACV or replacement cost. If the wording is hard to interpret, ask the insurer to explain how it applies to your roof and the reported loss.
How roof condition and maintenance records can inform a review
Visible wear, evidence of earlier repairs, and maintenance history can provide context during a review. Dated photos taken before a storm may help show the roof’s earlier condition, while later photos can document what you noticed afterward. Neither set of images decides coverage, but clear records can help explain the timeline and the roof’s condition.
Gather what you have, even if the records are incomplete:
- Dated inspection reports and photographs from before and after the reported event.
- Repair invoices or notes describing earlier roof work.
- Maintenance records and any communications with your insurer about the roof.
A professional roof inspection can document visible conditions and help you understand practical repair or replacement options. Thoughtful Roofer Inc. provides roof inspections and helps homeowners organize roof-related claim documentation. Coverage decisions remain with the insurer. If you’re unsure what the roof condition shows, a professional roof inspection can give you clearer information without promising claim approval.
Storm damage versus normal wear: what may happen with a 15-year-old roof?
After a storm in North Alabama, a leak or missing shingle can raise an urgent question: did the weather cause new damage, or did it reveal a problem that was already developing? The distinction matters because insurers review the reported cause alongside the roof’s condition and policy terms. Visible clues can help describe what you found, but they don’t prove when or how the damage occurred.
A roof inspection can describe damage; the insurer determines whether the policy covers it. If you’re wondering, “will homeowners insurance cover a 15 year old roof,” consider the event, available evidence, and policy rather than relying on the roof’s age or one visible clue alone.
| Reported cause | Possible roof evidence | Records to gather | Policy questions to review |
|---|---|---|---|
| Sudden storm event | Newly displaced or damaged shingles, fallen branches, or a leak noticed after the event. These are observations, not proof of cause. | Date and apparent event, ground-level photos, interior leak photos, and prior roof records. | Does the policy address the reported cause, and what deductible or exclusions apply? |
| Gradual wear or an ongoing issue | Visible deterioration, recurring leaks, or evidence of earlier repairs. An inspection can document conditions but may not establish when they began. | Repair invoices, maintenance notes, dated inspection reports, and photos showing changes over time. | How does the policy address wear, maintenance, prior damage, and roof settlement? |
If a storm may have damaged the roof
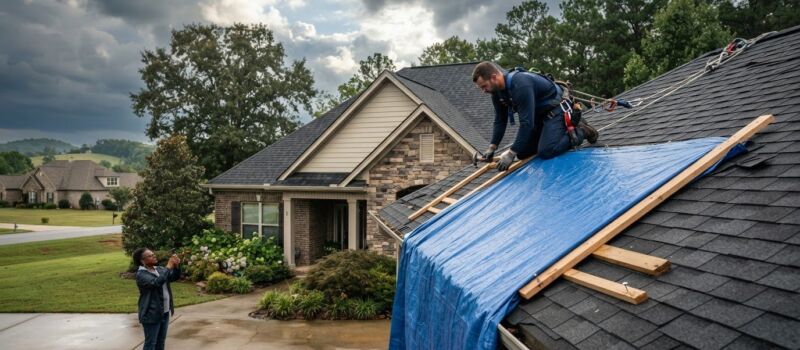
Write down when you noticed the problem and what weather event you believe may be related. Take photos from the ground and document any interior water marks. Don’t climb onto a wet or damaged roof. If water is getting inside, protect belongings and contain it safely where possible, without taking risks or making repairs beyond your ability. For more practical steps, read this storm damage roof repair guidance.
If the roof shows wear, leaks, or previous repairs
Gradual deterioration or maintenance concerns may be treated differently from sudden damage, depending on policy terms and the facts. Note where leaks appear, when you first noticed them, and whether anything changed after a weather event. Keep earlier repair records because they can help establish the roof’s history. A professional roof repair assessment can help identify practical repair needs. An inspection documents visible conditions, but it doesn’t decide coverage.

Steps before and after reporting an older roof claim
A clear record can make it easier to explain what you observed and when. Before contacting your insurer, gather the basic facts you can safely access. Then follow the insurer’s instructions for reporting the loss and protecting your home. These steps won’t determine coverage, but they can help keep the claim process organized.
- Review your policy. Find the sections on covered causes of loss, exclusions, deductibles, and roof settlement terms. Note any instructions about reporting damage or making temporary repairs.
- Document what you see. Take photos from the ground and document any interior leaks or affected rooms. Record the date, weather observations, when you noticed the damage, and any steps taken to limit further harm.
- Protect the home safely. Don’t climb onto a roof to inspect or cover it. If temporary measures are needed, follow your insurer’s instructions and policy terms when possible, and keep a record of what you did and any related expenses.
- Contact the insurer. Report your observations and ask what information they need next. Keep copies of claim communications, estimates, invoices, photographs, and inspection records.
How to document roof concerns safely
Use a phone or camera from the ground rather than walking on a roof, especially if it may be wet or unstable. Photograph visible exterior concerns from safe viewpoints and capture water stains, drips, or affected belongings indoors. Keep the original image files, note dates, and use clear file names so you can quickly find and share the records. Avoid describing a suspected cause as certain unless it has been established.
For a question like “will homeowners insurance cover a 15 year old roof,” organized documentation can help explain the reported damage and its timeline, but the insurer applies the policy and makes the coverage decision. A roofing inspection can add a description of visible conditions and repair or replacement observations. Those findings are separate from an insurer’s coverage decision or an adjuster’s determination.
How a roofing inspection can support clear communication
A roofer can document visible roof conditions and help identify practical next steps. That information may be useful when discussing the roof’s condition, but it doesn’t guarantee claim approval. Thoughtful Roofer Inc. provides roof inspections and claim documentation for homeowners in Huntsville, Madison, Owens Cross Roads, Gurley, and Athens. Learn more about professional roofing services and inspections.
If you’d like a clearer picture of the roof’s condition, arrange a roof inspection with Thoughtful Roofer Inc.
How Thoughtful Roofer Inc. helps Huntsville homeowners understand roof damage
A roof concern can feel harder to sort out when the roof has been in place for years and an insurance claim may be involved. Thoughtful Roofer Inc. provides roof inspections, repairs, replacement, and storm damage restoration for homeowners in Huntsville, Madison, Owens Cross Roads, Gurley, and Athens. The team can help you understand the roof’s condition and identify practical next steps, without rushing you toward a particular decision.
What a local roof assessment can clarify
An assessment can document visible damage, describe the roof’s overall condition, and identify areas that may need repair or further attention. If shingles appear damaged or a leak is present, clear observations can help you explain what you’ve noticed and share relevant information with your insurer. Inspection findings are a roofer’s assessment of the roof. They don’t bind the insurer, establish coverage, or replace an adjuster’s determination.
That distinction matters if you’re still wondering, “will homeowners insurance cover a 15 year old roof?” A roofer can provide useful documentation and assist with claim coordination, but the insurer reviews the policy and claim circumstances to make its coverage decision. Thoughtful Roofer Inc. can help organize roof-related information while keeping those roles clear.
A steady next step after discovering roof damage
Before discussing the roof, gather what you already have: your policy or declarations page, the approximate roof age if known, dated photos, prior repair invoices, and any inspection records. Note when you first observed a leak or other change, and whether it appeared after a specific weather event. You don’t need to settle the cause yourself. A careful assessment can help separate observable roof conditions from questions that only the insurer can answer.
A 15-year-old roof deserves an evidence-based assessment, not an assumption that it’s automatically too old or that every problem will be covered. Thoughtful Roofer Inc. serves homeowners in Huntsville, Madison, Owens Cross Roads, Gurley, and Athens with roof inspections, repairs, and storm damage restoration. The team can help document roof conditions, coordinate claim information, and discuss repair or replacement options without promising a claim outcome.
If you’d like to talk through a roof concern or arrange an inspection, contact Thoughtful Roofer Inc.
Take the next step with a clearer picture of your roof
So, will homeowners insurance cover a 15 year old roof? Age alone doesn’t settle the question. The insurer considers the policy, the roof’s condition, and whether the reported damage came from a covered event or gradual wear. Clear photos, repair records, and an inspection can help you explain what you’ve observed, but only the insurer decides coverage.
Thoughtful Roofer Inc. is a veteran-owned local roofing company serving Huntsville, Madison, Owens Cross Roads, Gurley, and Athens. The team provides roof inspections and storm damage restoration, and can help document roof conditions and coordinate claim information without promising an insurance outcome. An assessment can give you a clearer understanding of the roof and practical options for moving forward.
If you have a roof concern or want to discuss an inspection, talk with Thoughtful Roofer Inc. about a roof inspection. A clear next step can help you understand the roof’s condition and plan how to protect your home.
Frequently Asked Questions
Will homeowners insurance cover a 15-year-old roof?
A 15-year-old roof may be covered for some damage, but age alone doesn’t determine the answer. If you’re asking, “will homeowners insurance cover a 15 year old roof,” check your policy’s covered causes, exclusions, roof settlement terms, and deductible. Insurers also consider roof condition and the reported cause of damage. A roofer can document visible conditions, but the insurer decides whether a particular loss qualifies under your policy.
Can an insurer deny a roof claim because the roof is 15 years old?
An insurer may consider roof age when reviewing a claim, but there’s no universal age cutoff that decides every case. The policy wording, roof condition, reported damage, and evidence all matter. If a claim is denied, review the insurer’s explanation and the policy provision it references. Keep copies of inspection findings and repair records, and ask the insurer what information or next steps may help clarify its decision.
Does homeowners insurance cover roof leaks on an older roof?
It depends on what caused the leak and what your policy covers. A leak associated with a sudden covered event may be assessed differently from one resulting from gradual deterioration, neglected maintenance, or an existing problem. Document when you noticed the leak, where water appears inside, and any related weather event. Review the policy’s exclusions and reporting instructions, and take reasonable, safe steps to limit further interior damage.
What happens if an insurer says my 15-year-old roof has too much wear?
Ask the insurer to explain what findings support its position and which policy terms apply. Compare that explanation with your roof records, dated photographs, repair invoices, and any inspection report. A roofer can document visible conditions and describe potential repairs, but can’t decide coverage. Continue protecting your home safely and keep records of temporary measures. If the insurer outlines a review or response process, follow its instructions and keep copies of communications.
How does actual cash value affect an older-roof insurance claim?
Actual cash value generally accounts for depreciation when valuing a covered loss, so the settlement may be lower than the cost of replacing the damaged roof. Your deductible, policy limits, exclusions, and roof-specific provisions can also affect payment. Don’t assume your policy uses actual cash value or replacement cost based on the roof’s age alone. Check the settlement language in your current policy and ask your insurer to explain how it applies.
Should I get a roof inspection before filing a homeowners insurance claim?
An inspection can help you understand the roof’s visible condition and document damage before you discuss it with your insurer. It isn’t a coverage decision, and it doesn’t guarantee approval. Review your policy’s reporting instructions, and don’t delay required notice while waiting for an inspection. Take photos from the ground, document interior leaks, and gather repair records. A professional assessment can help you communicate observations clearly and consider practical repair needs.
Does homeowners insurance cover storm damage to a 15-year-old roof in Alabama?
It may, depending on the policy, the storm-related damage, the roof’s condition, and the claim circumstances. There isn’t one answer that applies to every Alabama homeowner, so review your own policy and insurer guidance rather than assuming a statewide rule. In Huntsville, Madison, Owens Cross Roads, Gurley, and Athens, homeowners can document visible conditions and storm observations, then ask the insurer how the policy applies to the reported loss.