What if a new roof improves your insurance options without automatically lowering your premium? It’s reasonable to ask, “will a new roof lower my homeowners insurance,” especially when replacement is a major decision. The answer depends on your insurer, your policy, and the roof you choose. A newer roof may help with eligibility or qualify for a discount, but savings aren’t guaranteed.
Before committing, ask your insurer how it evaluates roof age, condition, materials, and documentation. Find out whether a discount applies to your policy, what requirements you must meet, and how any change would affect your total premium. Get the details directly from your insurer rather than relying on general expectations.
This article explains when a roof replacement may affect coverage or premiums, which discounts to ask about, and what to verify before work begins. A professional inspection can help document your roof’s condition, while your insurer makes decisions about coverage and rates. With clear information in hand, you can choose a roof for lasting protection and make an informed decision about potential insurance benefits.
Key Takeaways
- A roof’s age, condition, materials, and maintenance history may inform an insurer’s assessment. Keep repair and replacement records together.
- When weighing repair against replacement, compare the roof’s actual condition with your insurer’s requirements. Insurance considerations don’t replace a sound roofing decision.
- Wondering “will a new roof lower my homeowners insurance”? Ask your insurer which discounts may apply to your policy and what requirements you’d need to meet.
- Before authorizing work, confirm what documentation your insurer accepts and whether replacement could affect coverage or policy terms.
- A professional inspection can help document roof condition. Your insurer remains the authority on eligibility, coverage, and premium terms.
Will a New Roof Lower Your Homeowners Insurance? The Short Answer
A new roof may help you qualify for an insurance discount or maintain coverage, but it doesn’t guarantee a lower premium. If you’re asking, “will a new roof lower my homeowners insurance,” your insurer is the one that can answer for your policy. Its decision may depend on the property, roof condition and materials, documentation, and underwriting rules.
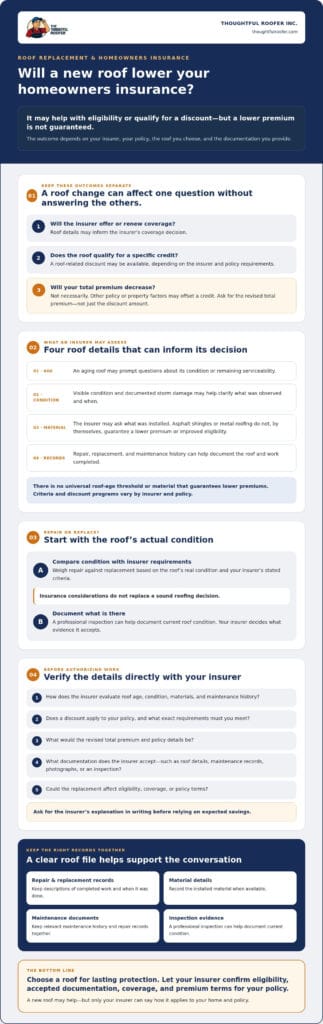
Separate three questions: Will the insurer offer or renew coverage? Does the roof qualify for a specific credit? Will your total premium decrease? These questions are related, but they aren’t interchangeable. A roof update may affect one without changing the others, and a new roof doesn’t guarantee a particular insurance outcome.
What insurers may consider about a roof
An insurer may look at the roof’s age, visible condition, materials, and documented repair or replacement work. Those details can help the company assess the property, but there’s no universal age threshold or material that guarantees lower premiums. Criteria and discount programs vary by insurer and policy.
A discount is not the same as a lower bill
A roof-related credit, if available, is only one part of the premium calculation. Other policy or property factors may offset it, so don’t assume that qualifying for a discount means your total bill will fall. Ask for the revised premium and policy details, not just the discount amount.
Also distinguish a premium change from how a future roof claim may be valued. Your policy’s settlement terms can affect what it pays after a covered loss. For background on the difference, see Replacement Cost Value (RCV) vs. Actual Cash Value (ACV). This general reference doesn’t determine the terms of your policy, so review your own documents and ask your insurer how they apply.
Before authorizing replacement based on expected savings, ask the insurer to explain in writing whether the proposed work changes eligibility, coverage, or the total premium, and what proof it requires. That gives you a clearer basis for weighing insurance considerations alongside the roof’s condition and your household’s protection.
How Roof Age, Condition, and Materials Can Affect Insurance Decisions
Roof details can influence how an insurer evaluates a home, but they don’t produce the same result for every homeowner. Insurers set roof criteria policy by policy, so confirm age, condition, and material requirements directly with your carrier. The Insurance Information Institute explains some of these factors in How Roof Age and Condition Affect Insurance. Use that as general background, then ask your own insurer how its rules apply to your property.
Why roof age and condition matter
An aging roof, a roof with documented storm damage, and a recently completed replacement describe different situations. Age may prompt questions about condition or remaining serviceability, while damage records can help clarify what was observed and when. A new roof establishes a recent replacement date, but that alone doesn’t guarantee a discount or a particular coverage decision.
Depending on its process, your insurer may ask for roof details, maintenance records, photographs, or an inspection. Keep dated records of repairs and replacement work, including descriptions of the work and materials when available. A professional roof inspection can help document current condition. Ask the insurer what it will accept and whether it needs a particular form of documentation.
Does roofing material change the insurance outcome?
Asphalt shingles and metal roofing are different material choices, but neither guarantees a lower premium or improved eligibility. The insurer may ask what material was installed and request documentation that identifies it. If a carrier has material-specific criteria or credits, confirm the exact requirements before choosing a roof based on expected insurance savings.
Before starting a project, ask your insurer:
- Does the roof material affect eligibility, coverage, or any available credit under my policy?
- What proof do you need to confirm the material and completed work?
- Would you need to review an inspection or other roof documentation?
Compare the insurer’s response with the roof’s condition and the protection your household needs. If you’re weighing asphalt shingles against metal roofing, a professional roof inspection can help clarify the existing roof’s condition and inform the roofing conversation. The inspection can document what’s there; only your insurer can determine how those details affect your policy.
New Roof vs. Repair: Which Choice Makes Sense for Insurance?
Start the repair-versus-replacement decision with the roof’s physical condition, not an assumed insurance discount. A targeted repair may address a specific problem, while widespread deterioration or repeated issues may call for a broader evaluation. Insurance decisions about coverage and premiums are related to this choice, but they don’t determine which roofing work the home needs.
| Roof situation | Repair may be worth evaluating when | Replacement may be worth evaluating when | What to ask your insurer |
|---|---|---|---|
| Localized issue | An inspection identifies a specific area that may be addressed with a targeted repair. | Ask whether other findings suggest a broader condition concern. | Will completed repairs affect your roof assessment, and what documentation do you need? |
| Widespread wear or recurring problems | A roofer can assess whether an isolated repair is appropriate or whether concerns extend beyond one area. | Replacement may be a more practical option if inspection findings show extensive deterioration or repeated issues. | Could the roof’s current condition affect eligibility or coverage, and what information would help clarify that? |
| Documented storm damage | A repair may be considered if inspection findings support addressing specific damage. | Substantial damage may warrant a full evaluation of the roof and the scope of needed work. | What does my policy say about this damage, and what records should I provide? |
When a repair may be worth evaluating
If an inspection finds a limited problem and supports a targeted fix, repair may be a reasonable option to discuss. Ask your insurer whether the repair changes how it views the roof, and keep records of the work. For guidance on the roofing side of that decision, read about roof repair in Huntsville.
When replacement may be the more practical path
Widespread deterioration, recurring problems, or substantial documented storm damage may make replacement worth considering, but those signs don’t automatically settle the decision. A qualified roofing inspection can help establish the roof’s physical condition. If storm damage is part of the concern, consult the Huntsville storm damage roof repair guide and contact your insurer about policy terms before assuming a claim will cover replacement.
So, will a new roof lower my homeowners insurance? It may affect the insurer’s assessment, but the answer depends on your policy and the carrier’s decision. Choose repair or replacement based on the roof’s condition and your household’s protection, then verify any insurance implications directly.
What to Ask Your Insurer Before Replacing a Roof in North Alabama
Before authorizing roof replacement, get guidance from your insurer about your specific policy. North Alabama homeowners may consider wind and hail exposure when evaluating roof protection, but local weather risk alone doesn’t establish that a roof is damaged or that a policy will cover replacement. Ask direct questions and save the answers so you can decide based on confirmed terms, not assumptions about savings.
Questions to ask before work begins
Contact your insurer or agent before signing a contract. If you’re wondering, “will a new roof lower my homeowners insurance,” use these questions to clarify whether replacement changes your policy and what steps to take:
- Does replacing my roof affect this policy’s eligibility, coverage, deductible, or total premium?
- Does my policy have roof-age requirements, and how do they apply to my home?
- Are any roof-related credits available for the material or work I’m considering? What exact conditions must I meet?
- Which documents do you need, such as material details, photographs, invoices, or inspection records?
- Do you require notice, documentation, or a review before work begins or after the replacement is complete?
- Can you send your answers and any premium or policy changes in writing?
Write down the representative’s name, the date, and their answers. If they refer you to another department or request more information, record that too. Ask for written follow-up before treating a possible credit or coverage change as confirmed.
Records to keep after roof replacement
If the project relates to suspected storm damage, keep relevant records of the damage and communications with your insurer. For additional background, consult a guide to navigating insurance claims after an Alabama storm. A roofer may help document roofing work, but your insurer determines coverage, eligibility, and premium terms.
Thoughtful Roofer assists homeowners with insurance claims and provides residential roofing services in Huntsville and nearby North Alabama communities, including Madison, Owens Cross Roads, Gurley, and Athens. If you need help documenting roof condition or completed work, discuss a roof inspection with Thoughtful Roofer, then confirm insurance requirements directly with your carrier.
Plan a Roof Replacement Around Protection, Documentation, and Verified Insurance Terms
Make the roof’s condition and your household’s protection the starting point, not the hope of lower premiums. If you’re asking, “will a new roof lower my homeowners insurance,” confirm the answer with your insurer before choosing work based on a possible discount. Pair that conversation with a professional inspection so you can consider the actual roof findings alongside the policy details.
How to choose a local roofing professional
Look for a roofing professional who can explain inspection findings, distinguish repair needs from replacement considerations, and provide project documentation. Before agreeing to work, review the scope and material description so you understand what is included. Compare the findings with your insurer’s requirements rather than relying on a sales promise about discounts or eligibility. For more selection guidance, consult a guide to roofing contractors in Huntsville.
A low-pressure next step for Huntsville-area homeowners
If you’re unsure whether age, visible condition, or storm damage calls for action, an inspection can help clarify the roof’s physical state. Thoughtful Roofer Inc. serves Huntsville, Madison, Owens Cross Roads, Gurley, and Athens with residential roof inspections, asphalt shingle and metal roofing, roof repair, storm damage repair, and assistance coordinating insurance claims.
Your insurer determines coverage, eligibility, and premium terms. Thoughtful Roofer can help with roofing work and claim coordination, but it can’t promise a particular insurance outcome. If you’d like help understanding your roof’s condition and practical next steps, contact Thoughtful Roofer to discuss an inspection. That gives you a clearer foundation for deciding what the home needs while you verify insurance details directly with your carrier.
Make Your Next Roofing Decision With Confidence
A new roof may affect insurance eligibility or qualify for a discount, but a lower premium isn’t guaranteed. Roof age, condition, materials, and documentation can all matter, and your insurer’s policy-specific answer is more reliable than general expectations. Before choosing repair or replacement, consider what an inspection finds, confirm what documentation your carrier needs, and ask how the proposed work could affect your coverage and total premium.
If you’re still asking, “will a new roof lower my homeowners insurance,” keep the priorities clear: protect your home first, document the roofing work, and verify insurance terms directly with your insurer. A roofer can assess roof condition and help coordinate claim documentation, but the insurer makes coverage and premium decisions.
Thoughtful Roofer is a veteran-owned local roofing company serving Huntsville, Madison, Owens Cross Roads, Gurley, and Athens, offering roof inspections, replacement, repairs, storm restoration, and insurance-claim coordination support. If you’d like help understanding your roof’s condition and practical next steps, Request a thoughtful roof inspection. A clear assessment can help you move forward with greater confidence and protect the home your household depends on.
Frequently Asked Questions
Will a new roof automatically lower my homeowners insurance?
No, a roof replacement doesn’t guarantee a lower premium. If you’re asking, “will a new roof lower my homeowners insurance,” your insurer must evaluate your specific policy, property, roof details, and underwriting rules. Ask whether the replacement affects eligibility, coverage, available credits, or other policy terms. Request an updated premium estimate in writing, then compare the full policy cost rather than assuming a roof-related discount will reduce your bill.
How much can a new roof lower homeowners insurance?
There’s no reliable universal amount to expect. Any change depends on your insurer, policy, property, roof details, and other premium factors. Ask your carrier whether your roof may qualify for a credit and how that would affect the complete premium and coverage. In Huntsville and nearby communities, verify the figures for your own policy before making a replacement decision. Don’t count on estimated savings that your insurer hasn’t confirmed.
Do insurance companies give discounts for a new roof?
Some insurers may offer roof-related credits or consider roof updates during underwriting, but availability and requirements vary by company and policy. Ask whether your material, installation details, roof age, or documentation meet your insurer’s criteria. Request the terms in writing, and confirm whether the change affects only the premium or also eligibility, coverage, or deductibles. A roofer can help document completed work, but the insurer determines how it affects your policy.
Does a metal roof lower homeowners insurance more than shingles?
Not necessarily. A metal roof or asphalt shingles don’t guarantee a discount or lower premium by themselves. Insurers set their own criteria, so ask how your carrier evaluates each material and what documentation it needs. Then weigh its response alongside the roof’s condition, installation scope, suitability for your home, and protection needs. For homeowners in Huntsville and North Alabama, the best choice should work for the property, not rely on assumed insurance savings.
Should I tell my insurance company before replacing my roof?
Yes, contact your insurer before work begins and ask what information or steps it requires. Confirm whether replacement affects eligibility, coverage, discounts, or documentation, and whether the carrier expects notice before or after the project. Keep a record of the representative’s name, the date, and the answers, and request written confirmation. Processes vary by insurer, so follow the instructions for your own policy rather than relying on a general rule.
Can I get a homeowners insurance discount after a roof replacement in Alabama?
You may qualify for a roof-related credit, but it depends on your insurer and policy. Don’t assume one discount applies to every Alabama homeowner. Ask your carrier what roof details and records it needs, whether any credit applies to your home, and how it changes the full premium and policy terms. Huntsville-area homeowners should get the carrier’s answer in writing before including potential savings in a roofing budget.
Will insurance pay to replace my roof if it is old?
Not automatically. Whether a claim covers roof replacement depends on your policy, the cause of damage, the roof’s condition, and the insurer’s claim decision. Ask your carrier to explain the terms that apply, and have any suspected damage documented. A roofing contractor can assess the roof’s physical condition and help record roofing work, but can’t determine coverage. Thoughtful Roofer serves homeowners in Huntsville, Madison, Owens Cross Roads, Gurley, and Athens.