What if the most expensive damage to your Huntsville home isn’t the leak you can see, but the microscopic hail fractures your insurance adjuster might overlook? It’s a common worry for North Alabama families after a season of severe weather. You likely feel the weight of protecting your household, yet the prospect of fighting for a fair settlement feels overwhelming. Between confusing paperwork and the pressure of meeting strict deadlines, it’s easy to feel like the system is designed to favor the insurer rather than the homeowner.
We understand that stress, and we believe you shouldn’t have to manage it alone. This guide helps you master the roof insurance claim process huntsville residents must navigate to secure the full coverage they deserve. By following the roadmap designed by Thoughtful Roofer Inc., you can transform a complex administrative burden into a streamlined path toward a high-quality roof replacement. We’ll preview the essential steps of our proprietary administrative advocacy workflow and show you how to document hidden storm damage so nothing is left to chance. Your peace of mind starts with knowing exactly what comes next.
Key Takeaways
- Identify the unique storm risks in the Tennessee Valley that often lead to hidden structural damage overlooked by standard adjusters.
- Master the roof insurance claim process huntsville residents use to secure full coverage through a proprietary administrative advocacy workflow.
- Learn why most initial insurance estimates require supplemental documentation to cover essential items like local code upgrades and proper ventilation.
- Differentiate between Replacement Cost Value and Actual Cash Value to ensure you receive the maximum funding available for your roof replacement.
- Understand the legal requirements of the Alabama Deductible Law to protect your household from common insurance fraud pitfalls.
Understanding the Roof Insurance Claim Process in Huntsville
Have you ever looked at your roof after a spring storm and wondered if it’s still protecting your family? In the Tennessee Valley, we face a unique set of weather challenges that test the integrity of even the strongest homes. A roof insurance claim is more than just a financial transaction; it’s a formal request for coverage through your homeowners insurance policy to restore your home’s safety and stability. Mastering the roof insurance claim process huntsville homeowners face requires understanding that our region sits right in the path of Tornado Alley and frequent hail cycles.
At Thoughtful Roofer Inc., we don’t just see shingles and nails. We see the physical shield that keeps your loved ones dry and secure. Many neighbors worry that filing a claim will cause their rates to skyrocket or lead to an immediate policy cancellation. However, Alabama regulations generally protect you when damage is caused by “Acts of God,” such as the sudden windstorms and hail common in North Alabama. These events are beyond your control, and your policy exists specifically to act as a stabilizing force during these difficult situations.
When Should You File a Claim in North Alabama?
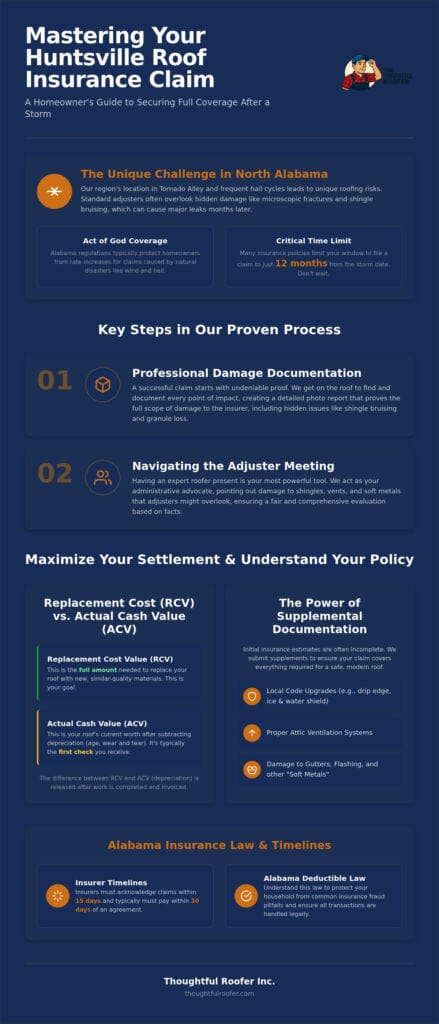
Identifying damage isn’t always as simple as spotting a missing shingle from the driveway. Often, the real threat comes from “unseen” damage like shingle bruising or significant granule loss that compromises the waterproof layer. You should act quickly. While Alabama has a general two-year statute of limitations for property damage lawsuits, many local insurance policies include a “suit against us” provision. This often limits your window to just 12 months from the date of the storm or the date the insurer closes the claim. Waiting too long can turn a valid claim into a denied one, as it becomes harder to differentiate between sudden storm impact and standard age-related wear.
The Role of the Local Roofing Expert
Why should you call a roofer before your insurance company? It’s the smartest first move you can make. An experienced local contractor provides the specialized documentation and technical evidence an insurance adjuster needs to see. Without a detailed report of the damage, you risk an initial denial that can take months of stressful paperwork to appeal. We act as your administrative advocate, ensuring the true scope of the damage is recorded from the very first inspection. For a deeper look at navigating the aftermath of severe weather, see our Storm Damage Roof Repair in Huntsville, AL: The Homeowner’s Recovery Guide. This proactive step is the foundation of a successful roof insurance claim process huntsville residents can trust for long-term peace of mind.
The 5 Crucial Steps of an Alabama Roof Insurance Claim
How do you move from a damaged roof to a fully restored home without the administrative headache? The roof insurance claim process huntsville homeowners navigate is a methodical journey that requires precision at every turn. We use a proprietary workflow to ensure no detail is missed, protecting your household’s safety and your financial investment. By following these five steps, you can transition from storm-related stress to total peace of mind.
Step 1: Professional Damage Documentation
A quick glance from the driveway won’t cut it. For Madison hail damage, we get on the roof to find shingle bruising, which is a dark, soft spot where hail has compressed the shingle mat and displaced protective granules. We create a detailed Photo Report that makes the damage undeniable for insurers. Ground-level inspections often miss the microscopic fractures that lead to leaks months later. Our team focuses on the structural health of the entire roof deck, not just the visible shingles, ensuring we catch issues before they compromise your ceiling.
Step 3: Navigating the Adjuster Meeting
This is where advocacy matters most. Having your contractor present ensures the adjuster doesn’t overlook “soft metals” like ridge vents and gutters that often show impact marks first. We maintain a collaborative tone to address potential adjuster bias and ensure a fair evaluation. Knowing your Alabama insurance consumer rights provides a layer of security during these discussions. Alabama regulations require companies to acknowledge your claim within 15 days of receipt, and once an agreement is reached, they typically have 30 days to tender payment. This timeline keeps the process moving, but only if your documentation is solid from the start.
Finalizing the Restoration
Step 2 involves filing the claim and securing your claim number, which acts as the tracking ID for your project. Keep this number in a safe place. After the adjuster meeting, Step 4 focuses on reviewing the scope of work. We compare the insurance estimate against our detailed inspection to ensure every necessary component, including labor and materials, is fully funded. Finally, Step 5 is the professional restoration. We complete the physical repairs and submit final documentation to the insurer to close your file. If you’re ready to start with a veteran-led team, the proprietary workflow at Thoughtful Roofer Inc. is designed to guide you home.
Maximizing Your Claim with Supplemental Documentation
Does your initial insurance estimate seem surprisingly low? It’s a common experience for many in the Tennessee Valley. Approximately 90% of initial quotes in the roof insurance claim process huntsville residents encounter need what’s called a supplemental claim. This is a formal request for additional funds to cover items the adjuster missed or price discrepancies for materials that have changed since the original estimate was written.
Common omissions include ice and water shields, high-quality ridge vents, and essential code-required upgrades. Our “Thoughtful” administrative advocacy means we handle this complex back-and-forth for you. We don’t just aim for “pre-storm” condition; we ensure your home is restored to meet 2026 Alabama building codes, providing the long-term stability your family deserves. This meticulous approach prevents you from having to pay out-of-pocket for items that your policy should naturally cover.
Addressing the “Underpaid” Claim
What should you do if the insurance check won’t cover the actual cost of high-quality asphalt shingles or metal roofing? Insurers typically use a software called Xactimate to determine industry-standard pricing. However, these estimates often lag behind real-world market shifts in North Alabama. We bridge this gap by providing line-item evidence of local labor and material costs, ensuring the funding matches the quality of work required. By documenting the specific requirements of your project, we act as a stabilizing force between you and the insurance carrier.
Code Requirements in Huntsville and Madison
Modern safety standards in Huntsville and Madison often require specific drip edge and flashing configurations that weren’t standard a decade ago. If your policy includes “Law and Ordinance” coverage, it should pay for these necessary upgrades. Alabama building codes permit a maximum of two layers of shingles, but we generally recommend a complete tear-off to inspect the roof deck for hidden damage. We carefully document these requirements to ensure your insurer fulfills their obligation to bring your home up to current safety standards. For more on what constitutes a high-standard installation, explore our guide on What Are Professional Roofing Services? A Homeowner’s Guide to Quality & Protection. We believe your roof shouldn’t just be a patch job; it should be a renewed shield for your household.
Practical Logistics: Deductibles, Depreciation, and Funding
How does the money actually move from your insurance carrier to your new roof? Understanding the financial flow is essential to maintaining control over the roof insurance claim process huntsville families rely on for home restoration. Most modern policies are written as Replacement Cost Value (RCV), which means the insurer pays the full cost to replace your roof, minus your deductible. In contrast, Actual Cash Value (ACV) policies only pay for the depreciated value of the roof based on its age. Knowing which one you have is the first step in avoiding unexpected out-of-pocket costs.
One of the most critical legal aspects to understand is the Alabama Deductible Law. In our state, it is considered insurance fraud for a contractor to “waive” or “cover” a homeowner’s deductible. We operate with the integrity you expect from a veteran-led business, which means we provide transparent pricing that respects both the law and your budget. While the financial side can feel complex, we act as a stabilizing force to ensure every dollar is accounted for and applied correctly to your home’s safety.
How Recoverable Depreciation Works
Insurance companies typically use a two-check system to ensure that the repairs they are funding are actually completed. The first check you receive is often the ACV portion, which serves as a deposit to get the project started. The remaining funds are held back as “recoverable depreciation” until the work is finished. Depreciation is recoverable once proof of repair is submitted to the insurance company through a formal invoice and a Certificate of Completion. This final document is the key that releases the remaining funds, allowing you to pay the final balance without dipping into your personal savings.
The Truth About Deductibles
If a low-bidding contractor offers to eat your deductible, it should be an immediate red flag. To make up that financial gap, they often have to use inferior materials or cut corners on labor, which compromises the very structure meant to protect your family. You should budget for your deductible as your primary out-of-pocket responsibility. We provide a clear, line-item breakdown of all costs so you know exactly where your money is going. If the insurance settlement leaves a gap for items you wish to upgrade, such as moving from asphalt shingles to a metal roof, we offer flexible options to help bridge that difference. If you have questions about your specific estimate, contact Thoughtful Roofer for a transparent review of your claim logistics.
Why Thoughtful Roofer is Your Partner in Restoration
Why choose a contractor who handles your insurance paperwork as carefully as they do your shingle alignment? When managing the roof insurance claim process huntsville families encounter after a Tennessee Valley storm, the administrative side is often more stressful than the physical repair. We built Thoughtful Roofer Inc. to be a stabilizing force for our neighbors. Our proprietary Thoughtful Workflow isn’t just a checklist; it’s a meticulous administrative advocacy system designed to ensure your household receives every bit of coverage your policy allows. We prioritize your family’s safety and the long-term health of your home over high-pressure sales tactics.
The Veteran-Owned Difference
Our foundation as a veteran-owned and operated business means military discipline is baked into every inspection we perform. This translates to meticulous claim documentation that adjusters find difficult to ignore. We approach every project with a mission-first mindset: protecting your home’s structural integrity is our primary objective. Integrity isn’t just a buzzword for us; it’s a commitment to honesty that protects you from the predatory practices often seen in the storm restoration industry. For a deeper look at our standards, explore our guide on Expert Roofing in Huntsville, AL: The 2026 Homeowner’s Guide to Quality & Trust. We treat your roof as if it were sheltering our own families, focusing on longevity and dependability.
Beyond the Roof: Seamless Gutters and Metal Options
Storms rarely limit their damage to your shingles alone. High winds and hail frequently batter your gutters, leading to hidden drainage issues that can threaten your foundation. We specialize in integrating seamless gutters into your storm damage claim, ensuring your entire water management system is restored. Many Huntsville homeowners also ask about upgrading to metal roofing during the restoration process. While insurance typically covers the cost of “like-for-like” materials, we can help you understand how to apply your claim funds toward a metal upgrade for enhanced energy efficiency and storm resistance. Our team handles the back-and-forth with your carrier to see if these improvements can be part of your recovery plan. Ready to secure your home with a partner you can trust? Book your Thoughtful Roof Inspection today! We are here to guide you through every step of the restoration with clarity and care.
Securing Your Home’s Future After the Storm
How do you move from the uncertainty of storm damage to the security of a fully restored home? Mastering the roof insurance claim process huntsville homeowners face is about more than just physical repairs; it’s about having an advocate who understands the administrative hurdles and the local 2026 building codes. We’ve explored the importance of detailed documentation, the necessity of supplemental claims for missed items, and the logistical flow of insurance funding. This knowledge empowers you to protect your household from being underpaid or overwhelmed.
Since 2021, Thoughtful Roofer has served Huntsville, Madison, and Athens as a stabilizing force for families in crisis. As a veteran-owned and operated company, we use our proprietary administrative advocacy workflow to ensure no detail is overlooked by your carrier. You don’t have to navigate confusing paperwork or adjuster meetings alone. We’re here to act as your protective mentor, guiding you through every step until your household is safe and your peace of mind is restored.
Ready to take the first step toward a worry-free restoration? Get Your Free Thoughtful Roof Inspection & Claims Consultation today. Your home’s longevity is our mission, and we’re ready to serve you.
Frequently Asked Questions
How long does the roof insurance claim process typically take in Huntsville?
The timeline for a typical claim usually spans between 30 and 60 days from start to finish. Alabama regulations require insurance companies to acknowledge your claim within 15 days of receipt. Once an agreement on the scope of work is reached, the insurer typically has 30 days to tender payment. Our proprietary workflow keeps this process organized, ensuring that complex supplemental claims for 2026 code upgrades don’t cause unnecessary delays for your household.
Can I choose my own roofing contractor, or does the insurance company pick one?
You have the legal right to select any licensed roofing contractor you trust to work on your home. While insurance carriers often suggest preferred vendors, these companies may have agreements that prioritize the insurer’s budget over your home’s structural integrity. Choosing a local, veteran-owned partner ensures your interests come first. We act as your administrative advocate throughout the roof insurance claim process huntsville homeowners navigate, prioritizing high-quality materials and meticulous installation standards.
Will my insurance rates go up if I file a claim for storm damage in Alabama?
Generally, Alabama law protects homeowners from rate increases based on a single claim resulting from an Act of God. Since tornadoes and hail are beyond your control, they aren’t viewed the same as at-fault incidents like a fire caused by negligence. However, rates can rise for an entire zip code after a major Tennessee Valley storm. Filing a valid claim is a necessary step to protect your home’s safety and long-term value.
What happens if the insurance adjuster misses some of the damage?
We routinely file supplemental claims to cover damage that adjusters might overlook during their initial visit. Approximately 90% of initial estimates in the roof insurance claim process huntsville residents experience require these supplements to address missed items like drip edges or ice and water shields. We provide the technical photo evidence and line-item documentation needed to bridge this gap. This ensures your roof is restored to meet current 2026 Alabama building codes.
Is hail damage covered under a standard Alabama homeowner’s policy?
Yes, hail damage is a covered peril under almost every standard homeowner policy in Alabama. In the Tennessee Valley, hail often causes shingle bruising that isn’t visible from the ground but significantly shortens your roof’s lifespan. Your policy exists to act as a stabilizing force after these events. We specialize in identifying these microscopic fractures to ensure your claim reflects the true extent of the storm’s impact on your home’s protective shield.
What is the difference between a roof repair and a full replacement claim?
The difference depends on the extent of the damage and the age of your existing materials. If a significant percentage of the roof is damaged, or if the shingles are too brittle to be repaired without causing further issues, a full replacement is often required. Alabama building codes also permit a maximum of two shingle layers. We evaluate your roof’s condition to determine which path provides the most dependable protection for your family.
Do I have to pay my deductible upfront to Thoughtful Roofer?
Your deductible is typically due at the time of the final installation rather than as an upfront deposit. We follow a transparent pricing model where the deductible is your primary out-of-pocket responsibility. Under the Alabama Deductible Law, it is illegal for a contractor to waive or cover this cost for you. We collect the initial insurance check to begin the restoration and settle the remaining balance once the project reaches its successful completion.
What should I do if my insurance claim is denied?
Don’t panic if your initial claim is denied; you have the right to request a second inspection or a different adjuster. Many denials occur because the damage wasn’t documented with enough technical specificity during the first meeting. We can review your denial letter and provide a comprehensive photo report to support an appeal. Our mission is to act as your protective mentor, helping you navigate these administrative hurdles to ensure your home is safe.